Form 5472 penalty and late filing
The $25,000 Form 5472 penalty, what triggers it, how the continuation penalty works, and what a foreign-owned LLC should do about missed past years.
Last updated: 2026-10-31
Form 5472 owes no tax, which is exactly why owners miss it. The penalty does not scale with your income. It is a flat amount per form, and it is large.
The numbers
- $25,000 for each Form 5472 not filed on time and in the required manner. A substantially incomplete form counts as not filed.
- $25,000 for failing to keep the records that support it.
- If the failure continues more than 90 days after the IRS notifies you, an additional $25,000 for each 30-day period or part of one.
- Criminal penalties exist for willful failures and false statements.
One LLC that skipped three years has three missing returns, not one.
Why owners miss it
- The formation service said a single-member LLC with no U.S. income has nothing to file.
- The LLC had no revenue, so "nothing happened". But putting money in, or paying fees personally, is a reportable transaction.
- Tax software does not prepare a pro forma Form 1120, and the form cannot be e-filed.
If you missed past years
- List the years. Every year since formation in which money moved between you and the LLC.
- Use each year's own Form 1120. The pro forma 1120 is year-specific; Form 5472 uses the current revision.
- Attach a reasonable cause statement to each late filing: the facts, when and how you learned of the requirement, what you did next, and that you will file on time from now on. It must be true and in your own words.
- File before the IRS contacts you. Fax or mail to the PIN Unit, as for an on-time filing; see fax number and address.
- Keep everything and answer any IRS notice by its deadline. The IRS says penalties for delinquent international information returns may still be assessed under normal procedures, sometimes before a reasonable cause statement is reviewed, and you may need to respond to correspondence.
About abatement
First-time abatement covers failure-to-file, failure-to-pay and failure-to-deposit penalties on returns. The Form 5472 penalty is a separate information return penalty, so the usual route is reasonable cause: you acted with ordinary business care and the failure was not willful neglect. If a penalty notice has already arrived, or the amounts are large, a tax professional is worth the fee.
The catch-up packet
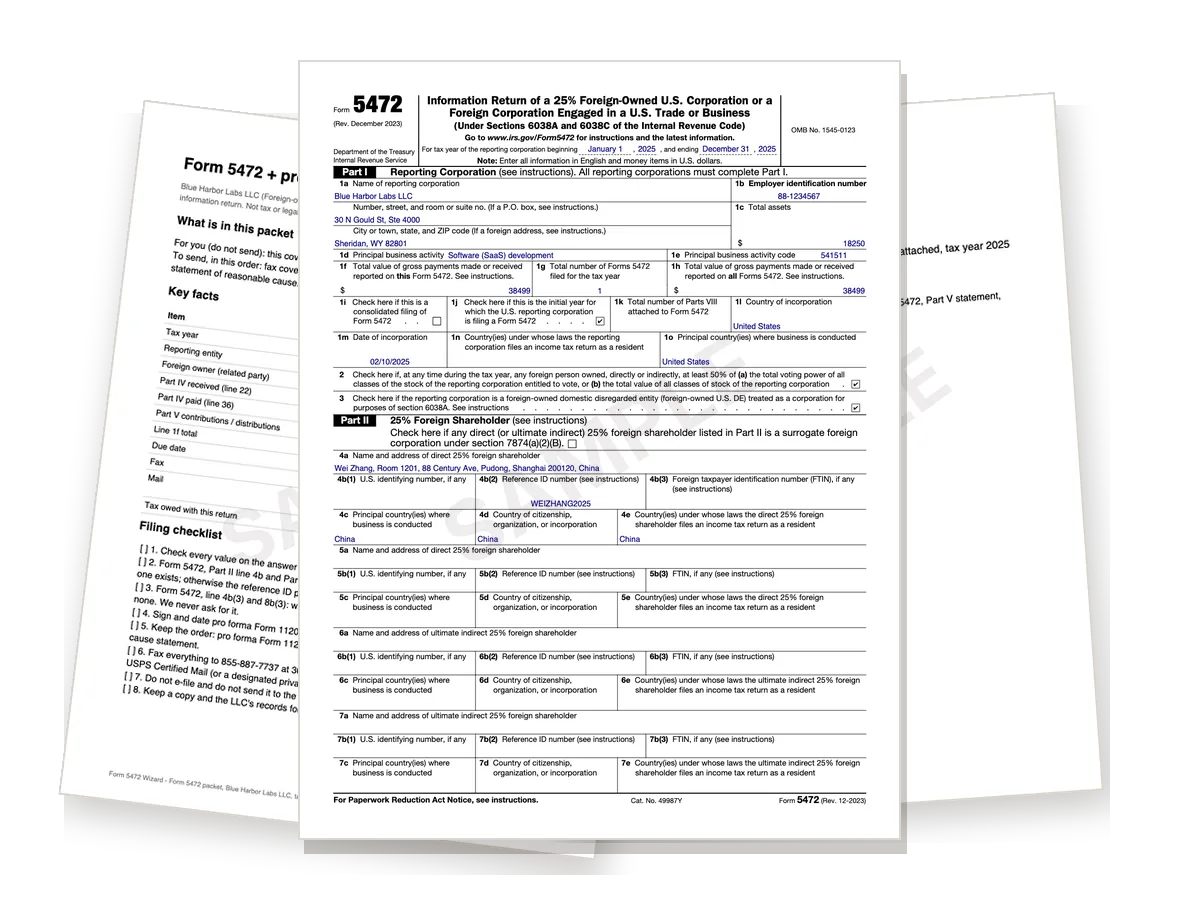
The Form 5472 wizard builds a packet per year with that year's pro forma Form 1120, the filled Form 5472, the Part V statement, a fax cover and a reasonable cause statement draft for you to complete and sign. $199 covers every past year.
Self-prepared information return. Not tax or legal advice. Not affiliated with the IRS. Sources: Instructions for Form 5472 (Penalties); IRS, Delinquent international information return submission procedures.
What you get