Form 5472 instructions for a foreign-owned LLC
Who files Form 5472 with a pro forma 1120, what counts as a reportable transaction, and what goes in Parts I to VII when a non-U.S. person owns the LLC.
Last updated: 2026-10-31
If you are not a U.S. person and you own a U.S. LLC by yourself, the IRS treats that LLC as a corporation for one narrow purpose: reporting what moves between it and you. That is Form 5472, filed with a "pro forma" Form 1120. No tax is calculated, but the penalty for missing it is $25,000.

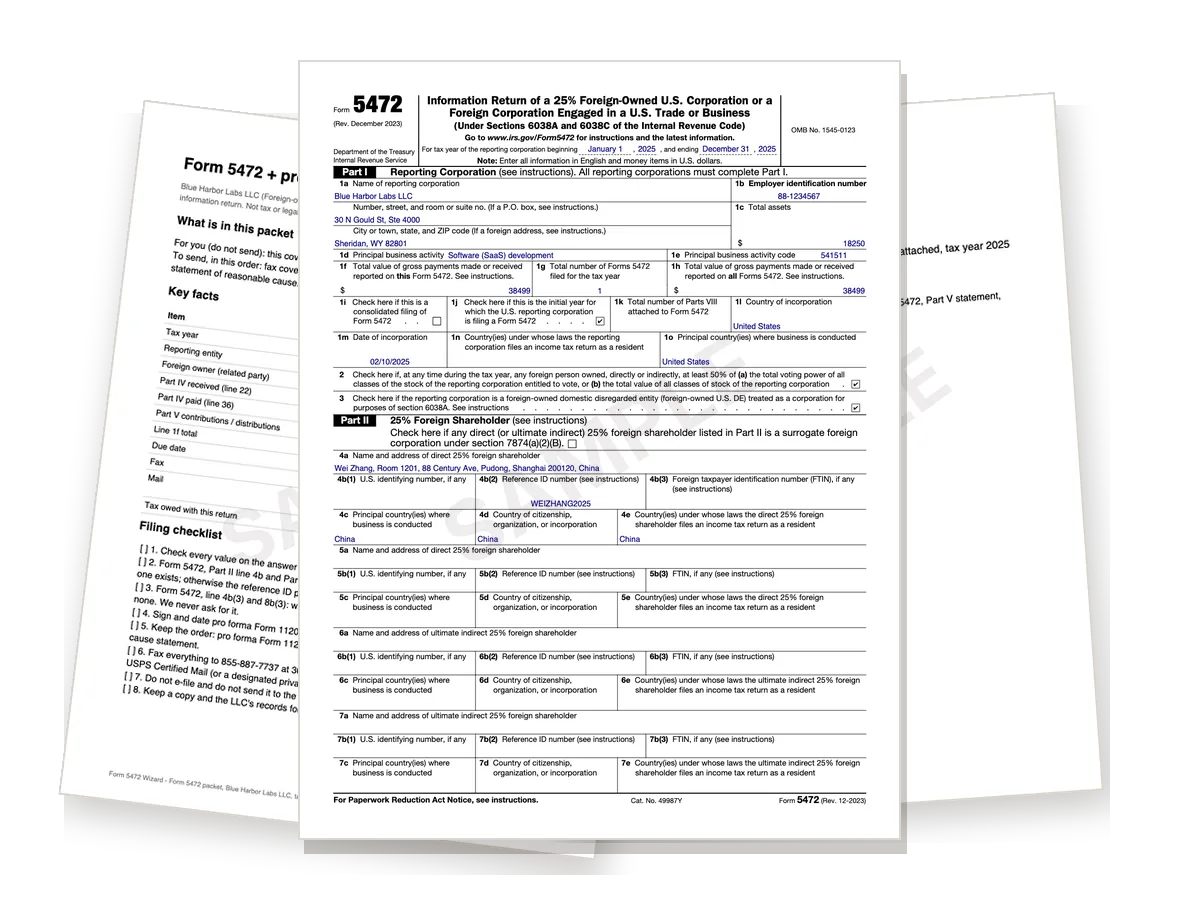
Pages from a sample packet made by our wizard, with made-up data.
Do you have to file?
All four must be true:
- The LLC is a U.S. entity with a single owner. Two or more owners make it a partnership, which files Form 1065 instead.
- The owner is a foreign person: not a U.S. citizen, green card holder or U.S. tax resident. The owner can be an individual or a foreign company.
- No election to be taxed as a corporation (no Form 8832 or 2553). An LLC that elected corporate status files a full Form 1120.
- At least one reportable transaction with the owner or another related party during the year.
Number 4 catches almost everyone. For a foreign-owned disregarded entity, reportable transactions include amounts paid or received for the entity's formation, dissolution, acquisition and disposition, and contributions to and distributions from the entity. Wiring $500 to open the bank account is a contribution. Paying the state fee or registered agent with your personal card is a contribution. Moving profit to your home account is a distribution.
The only way out is a year with no transactions at all with a related party.
Not sure? The free Form 5472 checker takes five questions.
What you send
- A pro forma Form 1120 for the right tax year, with only the LLC's name, address, item B (EIN) and item E (initial return, final return, name or address change) filled in, and "Foreign-owned U.S. DE" written across the top. More on that in pro forma Form 1120.
- Form 5472, attached behind it.
- A statement for Part V, listing contributions and distributions.
It cannot be e-filed. Fax or mail it; see fax number, address and due date.
Part I: the reporting corporation (your LLC)
| Line | What to enter |
|---|---|
| 1a | LLC name and U.S. address, including suite |
| 1b | The LLC's EIN |
| 1c | Total assets at year end, usually the bank balance plus anything else the LLC owns |
| 1d, 1e | Principal business activity and its six-digit code from the Form 1120 instructions (for example 541511 custom computer programming) |
| 1f | Total value of the transactions on this form: Part IV lines 22 and 36, plus the Part V amounts |
| 1g | Number of Forms 5472 filed for the year (usually 1) |
| 1h | Total of line 1f across all your Forms 5472 |
| 1j | Check if this is the first year the LLC files |
| 1l, 1m | Country of incorporation (United States) and date formed |
| 1o | Principal countries where the LLC does business |
| 2 | Check: a foreign person owns at least 50% |
| 3 | Check: foreign-owned U.S. DE |
Part II: the 25% foreign shareholder (you)
Line 4a takes the owner's name and address. On line 4b, enter a U.S. taxpayer ID if the owner has one; if not, a reference ID number: letters and digits only, up to 50 characters, and the same every year. Line 4b(3) is the owner's foreign tax ID, or "None". Lines 4c to 4e: countries of business, citizenship and tax residence.
Part III: the related party
All filers complete Part III, even when the related party is the shareholder in Part II. For a one-owner LLC, that is you again: check "foreign person", repeat the name, address and IDs, and in 8e check "25% foreign shareholder".
Part IV: monetary transactions
Amounts the LLC received from the owner (lines 9 to 21) and paid to the owner (lines 23 to 35): inventory sales and purchases, rents, royalties, payments for services, commissions, loans (beginning and ending balance), interest. Lines 22 and 36 are the totals. Contributions and distributions do not belong here; they go in Part V.
Part V: contributions and distributions
Check the box and attach a statement describing each transaction: date, contribution or distribution, amount, and a short description.
Part VII: additional questions
All filers answer it. A typical one-owner service LLC answers No to every question. If the LLC imports goods it bought from the owner, line 37 is Yes and lines 38a and 38c follow. If there is a loan with the owner, read lines 42a and 42b. Lines 43a and 43b are not completed by a foreign-owned DE.
Records
The LLC must keep records that support what it reports: bank statements, invoices, and proof of each transfer. Failing to keep them carries the same $25,000 penalty as failing to file.
Let the wizard fill it
The Form 5472 wizard asks for the LLC, the owner and the year's transactions, sorts each transfer into Part IV or Part V, and builds the packet: the year's pro forma Form 1120 marked "Foreign-owned U.S. DE", a pre-filled Form 5472, the Part V statement, a fax cover with the page count, and a checklist. $99, or $199 for past years with a reasonable cause statement.
Self-prepared information return. Not tax or legal advice. Not affiliated with the IRS. Source: Instructions for Form 5472.
What you get